
Calibre Mining (TSX: CXB) has entered into an agreement to acquire Marathon Gold (TSX: MOZ) in a transaction valued at C$345 million. The merger aims to establish an Americas-focused, mid-tier gold-producing company projecting an average annual production of 500 koz of gold from 2025 to 2026.
Under the terms of the deal, Marathon shareholders will receive 0.6164 Calibre shares for each Marathon share, valuing each Marathon share at $0.84 and the total transaction at $345 million. This represents a 32% premium based on the spot price and a 61% premium based on the 20-day volume-weighted average price (VWAP) of Calibre and Marathon as of November 10, 2023.
In the combined entity, Calibre’s shareholders will hold a 66% interest, while Marathon’s shareholders will retain a 34% stake. Additionally, Calibre purchased 66.6 million Marathon shares at C$0.60 each, amounting to C$40 million, in a concurrent private placement, securing a 14.2% stake in Marathon.
 Sponsored · Selkirk Copper Mines
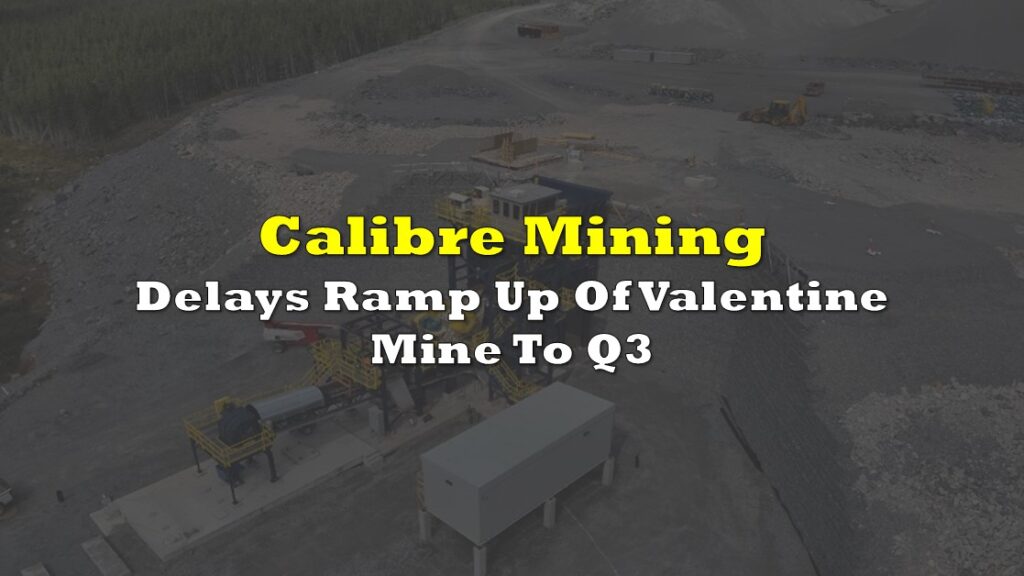
The transaction facilitates Marathon’s transition from a developer to a mid-tier gold producer. For Calibre, the acquisition includes the Valentine gold project, an imminent producing asset in Canada expected to commence operations in Q1 2025, with an estimated annual gold production of 195koz during the first 12 years.
Calibre Chairman Blayne Johnson expressed confidence in the transformative merger, emphasizing its alignment with Calibre’s strategy to build a diversified mid-tier gold producer. Johnson anticipates significant value creation for shareholders, stating, “This transformative merger creates a projected 500 koz gold producer and offers our shareholders diversification and exposure to high-quality, long-life production in a tier-one jurisdiction.”
“Slippery slope of greed”
While the companies tout the news, observers and investors can’t help but express their dismay at the acquisition price the firms have landed at. Investor Don Durrett emphasized that the 32% premium for acquiring Marathon Gold is still “a stunning discount.”
 Sponsored · Altamira Gold Corp.
“This happens over and over. The slippery slope of greed. This was not done in the interest of shareholders,” said Durrett.
Durrett added: “The bottom line is this. Marathon was not sold at a premium. It was sold at a discount (a huge discount). Forget about the current gold price. Forget about the current market price for gold in the ground. This is a long-life mine. Gold prices are going higher. This company is clearly worth $1B or $1.5B, when you project out the FCF over the next 10 years.”
Investment manager Lawrence Lepard also weighed in on the deal, saying “The management team here just did their investors wrong and put their own interests in front to their investors interests.”
“The $17.5 million break up fee is OUTRAGEOUS and prevents shareholders from getting a market bid. I am so tired of stupid Canadian mine management teams. I can’t wait to see how much they pay themselves with change of control provisions,” Lepard said.
The news resulted in an 11% surge in Marathon Gold shares, reaching a market capitalization of $285.6 million, while Calibre Mining’s shares experienced a 12% decline, with a market capitalization of $552.6 million.
The merger is poised to nearly double Calibre’s production, reducing its reliance on Nicaragua, where the majority of its assets are situated. Marathon, in turn, gains strong financial support for its Valentine gold mine project in Newfoundland, scheduled for production in early 2025.
The combined company is expected to possess over 4 million oz. of mineral reserves, 8.6 million oz. of measured and indicated resources, and 4 million oz. of inferred mineral resources. Calibre highlighted a peer-leading production growth of 80% during 2024-2026.
Calibre’s investment of $40 million in Marathon, through a private placement, will contribute to the development of the Valentine project, estimated to cost $403 million. According to Marathon CEO Matt Manson, this funding ensures that Valentine will reach production without additional debt, royalties, or shareholder equity.
Information for this briefing was found via Mining Technology, Mining.com, and sources mentioned. The author has no securities or affiliations related to this organization. Not a recommendation to buy or sell. Always do additional research and consult a professional before purchasing a security. The author holds no licenses.