
Newcore Gold (TSXV: NCAU) has released a pre-feasibility study for its Enchi Gold Project in Ghana, laying out the economics of a conventional open pit operation that the company intends to use as the basis for a mining lease application this year.
Using a base case gold price of $3,800 per ounce, the study pegs Enchi’s after-tax net present value at $496 million using a 5% discount rate, with an after-tax internal rate of return of 37%. Lift the gold price to a spot assumption of $4,200 per ounce and those figures climb to a $647 million after-tax NPV and a 45% IRR. Initial capital would be paid back in 1.6 years at the base case, shortening to 1.4 years at spot pricing.
The proposed mine is a 5.5 million tonne per annum milling and carbon-in-leach operation, fed by ore trucked from four deposits to a central processing plant. Over a 9.3-year life, Enchi would produce roughly 953,350 ounces of payable gold, averaging about 104,000 ounces annually. Production is of course front loaded, with the mine expected to average around 130,000 ounces in the first three years, helped by a higher mined grade of 0.80 g/t gold against a life-of-mine average of 0.64 g/t.
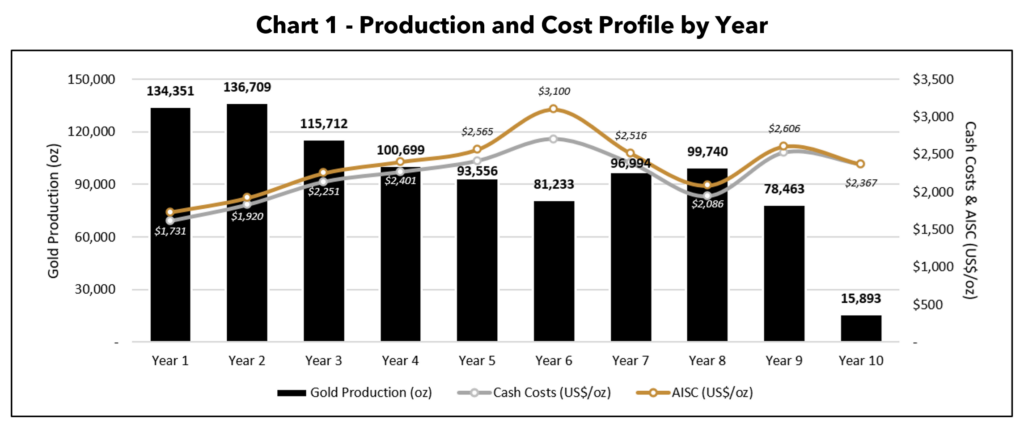
Initial capital is estimated at $351 million, with a further $135 million in sustaining capital and $21 million for closure. Construction is pencilled in at 24 months, and because mining is contracted out, no fleet purchase is required.
 Sponsored · Selkirk Copper Mines
Costs run lighter in the opening years and rise over the life of the mine as grade eases. Newcore estimates cash costs of $1,859 per ounce and all-in sustaining costs of $1,967 per ounce in years one through three, climbing to life-of-mine figures of $2,149 and $2,290 per ounce respectively. Gold recovery is modelled at 90.5%.
The economic model factors in a 2% net smelter return royalty to Triple Flag Precious Metals and a sliding-scale Ghanaian government royalty that runs from 5% to 12% depending on the gold price, alongside a 35% corporate tax rate and the government’s right to a 10% free carried interest.
President and CEO Luke Alexander called the study “an important milestone in advancing the Enchi Gold Project in Ghana towards a mining lease,” noting the realignment to a milling and CIL flowsheet was designed to maximize the project’s economic value.
Notably, the study leans on a March 2026 resource estimate that excludes more than 50,000 metres of an ongoing 80,000-metre drill program, including high-grade intercepts at depth that Newcore expects to feed into future work.
Newcore Gold last traded at $0.485 on the TSX Venture.