
Aya Gold & Silver (TSX:AYA) has released an updated preliminary economic assessment for its Boumadine project that roughly doubles the project’s estimated value, ten months after the original PEA landed.
The base case now carries an after-tax net present value of US$3.5 billion at a 5% discount rate, up from US$1.5 billion in November 2025. The after-tax internal rate of return climbs to 93% from 47%, and payback shortens to 0.7 years from 2.1.
Those economics rest on $3,500 per ounce gold, and $50 per ounce silver, an increase of 25% and 67%, respectively, from the gold and silver prices used in the prior study.
 Sponsored · McLaren Resources Inc.
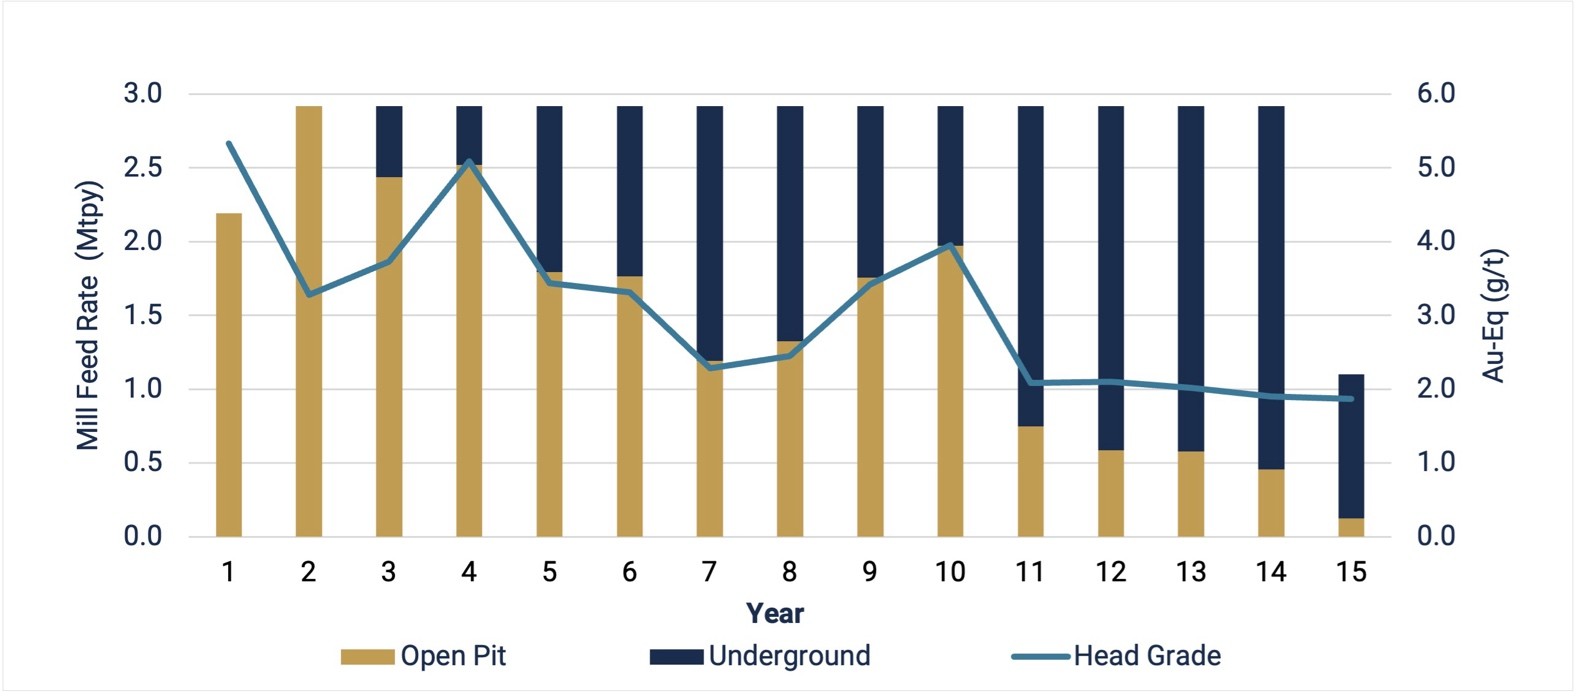
The design has changed very little, with the plan calling for an open pit and underground operation feeding an 8,000 tonne per day mill. What changed is how long it runs. The plan now processes 41.2 million tonnes over 14 years, against 31.1 million tonnes and 11 years previously, at average head grades of 1.77 g/t gold, and 63.5 g/t silver.
Life of mine output is pegged at 2.25 million ounces of gold, 81.2 million ounces of silver, 422,000 tonnes of zinc and 195,000 tonnes of lead, or 3.9 million gold equivalent ounces. Production averages 348,000 gold equivalent ounces a year through the first 5 years and 271,000 ounces over the full mine life.
Initial capital is estimated at $463 million, including a $99 million contingency, spread across a 2 year construction period. Sustaining capital averages $35 million annually, with total sustaining capital estimated at $507 million
Cash costs come in at $998 per gold equivalent ounce over the first 5 years and $1,169 over the mine life. All-in sustaining costs run $1,105 and $1,300 respectively.
The quick PEA update reflects roughly 190,000 metres of drilling completed since the February 2025 resource estimate, which lifted indicated resources 34% to 1.1 million gold equivalent ounces, alongside better concentrate payability terms, with silver moving to 85% from 77%, and gold to 82% from 70%.
“Boumadine is a standout precious metals project among its global peers,” said chief executive Benoit La Salle. “We have more than doubled the after-tax NPV to $3.5B, while keeping capital costs broadly in line with the prior PEA.”
A feasibility study is targeted for the second half of 2027, with an environmental assessment expected to wrap up alongside it. Aya plans 400,000 metres of drilling through the end of 2027, and is evaluating an expansion to 10,000 tonnes per day in years 3 and 4.
Aya Gold & Silver last traded at $40.16 on the TSX.