
Last week the London Metal Exchange (LME) decided to favor one category of customer, a metals producer which uses the futures exchange to fix the price of the commodity it is selling, over financial speculators like hedge funds. While such a stance seems perhaps sensible from the 30,000-ft level, the Exchange’s putting its thumb on the scale will drive speculators away from the market, in the long run leading to even wider price fluctuations and likely higher margin requirements for remaining participants. In turn, this could set the stage for “nickel-type” contagion spreading to other markets.
Specifically, on March 8, the LME not only suspended trading in nickel, but cancelled trades between willing buyers and sellers because the price of nickel increased too much, too rapidly. Such an action would be akin to investor’s completing a profitable series of stock trades with other stock market participants, only to see the regulator invalidate those trades later on because the underlying stock price was too high.
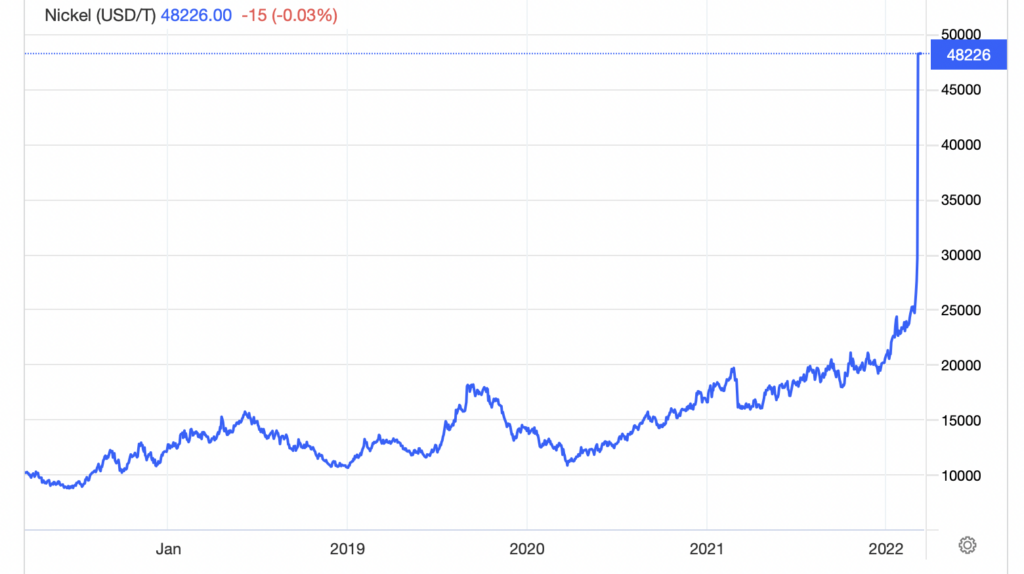
Nickel’s price briefly soared above US$100,000 per tonne on March 8, leading the LME to close the market on Tuesday. Through Friday, March 11, the LME nickel market had still not reopened. Nickel is a necessary input in the stainless steel manufacturing process and a key component in the batteries of most electric vehicles.
 Sponsored · Altamira Gold Corp.
The reason for all this traces to a nickel short position of about 150,000 tonnes that China-based Tsingshan Holding Group ultimately established to hedge at least some of its nickel production. Tsingshan, China’s leading nickel producer, is led by Xiang Guangda, a politically well-connected tycoon. Nickel speculators, cognizant of Tsingshan’s short position and its susceptibility to a squeeze, bid the commodity higher. The company faced a reported US$8 billion margin call based on the size of its nickel short position and the all-time high price of the metal.
One plan reportedly being considered is for Tsingshan to swap some of the low-grade nickel it produces for high-grade nickel held by China’s government. That nickel would then be delivered against its futures contract, which in turn would allow brokers like JP Morgan to be paid and would close out both the position and the margin call risk. It would also lock in a substantial loss for Tsingshan. Still, such a deal sounds net-net appealing for a company in trouble and would never be offered by a government under more normal circumstances.
However, Mr. Xiang seems dissatisfied. He does not want to close out his short position at a loss. Importantly, such an unwillingness to compromise would presumably negate the China government’s plan noted above. Also, it would seem to expose Tsingshan to another round of short squeezes. In addition, brokers, including JP Morgan, still need to be paid to satisfy margin calls. Bloomberg reported that Tsingshan owed JP Morgan US$1 billion in margin calls as of March 7. If Tsingshan were to fail, JP Morgan would presumably face losses of up to that amount.
What further complicates matters is that several banks, including JP Morgan, had previously reached a deal to provide secured credit to Tsingshan, allowing it to withstand margin calls when the LME reopens. It is unclear how that agreement would be affected by Tsingshan’s apparent intransigence regarding covering the short nickel position.
Nickel closed the week at around US$48,000 per tonne, based on trading at other exchanges.
It is difficult to handicap what the next steps will be in this process. Some party or parties, including Tsingshan, must be willing to accept substantial pain. So far, no party has fully acknowledged this.
A key implication of this nickel saga and LME’s actions is that speculators may be less inclined to participate in commodity markets. Given LME’s willingness to cancel trades after the fact, the markets may carry too much risk without sufficient reward. In the end, fewer market participants will almost certainly lead to even more commodity price volatility.
Information for this briefing was found via Edgar and the companies mentioned. The author has no securities or affiliations related to this organization. Views expressed within are solely that of the author. Not a recommendation to buy or sell. Always do additional research and consult a professional before purchasing a security. The author holds no licenses.