
Superior Gold Inc. (TSXV: SGI) has had a busy week. On June 21, the company announced that they delivered the final 1,320 ounces of gold to repay their loan. They expect that this repayment increased their future operating cash flow by U$2.4 million per quarter. Then on June 23, they announced drill results from its Plutonic Gold mine.
The company reported the following results, among others:
- Hole UDD24336 intersected 17.5 g/t gold over 1.00 meter downhole
- Hole UDD24340 intersected 23.0 g/t gold over 1.80 meters downhole
- Hole UDD24342 intersected 14.8 g/t gold over 13.4 meters downhole
- Hole UDD24351 intersected 60.0 g/t gold over 1.00 meter downhole
The company currently has six analysts covering the name, with a weighted 12-month price target of C$1.23 or a 64% upside. Out of the six, five analysts have buy ratings and one analyst has a hold rating. The street high comes from Stifel-GMP with a C$1.50 price target and the lowest comes in at C$1 from Laurentian Bank.
 Sponsored · Cambria Gold Mines
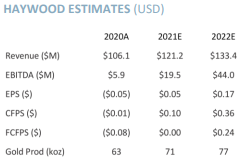
Haywood Capital Markets reiterated their C$1.10 price target and buy rating on Superior Gold after the drill results, saying that the drill results show “potential outside of remnant mining areas at the Plutonic Mine.”
With the results, they say “The Baltic Gap now extends over a strike length of 305m and up to 200m down dip.” They state the results have attractive grades as they are above the average grades relative to their existing resources. They also confirm the company’s thesis that mineralization is controlled by northwest-trending faults.
Haywood says that there are “significant near-term catalysts” with the best being the continued testing at the Western Mining Front with the possibility of adding a fourth or fifth drill rig, with results from the program expected early next month. The other catalysts consist of open-pit production resuming this quarter and the receipt of permits for the Main Pit Pushback by end of the year, which is expected to result in a pre-feasibility study in the first half of 2022.
Haywood maintained its buy rating on the firm, stating that based on EV/2022 OCF of 1.3x, the company remains as “one of the cheapest junior gold producers.”
Information for this briefing was found via Sedar and Refinitiv. The author has no securities or affiliations related to this organization. Not a recommendation to buy or sell. Always do additional research and consult a professional before purchasing a security. The author holds no licenses.