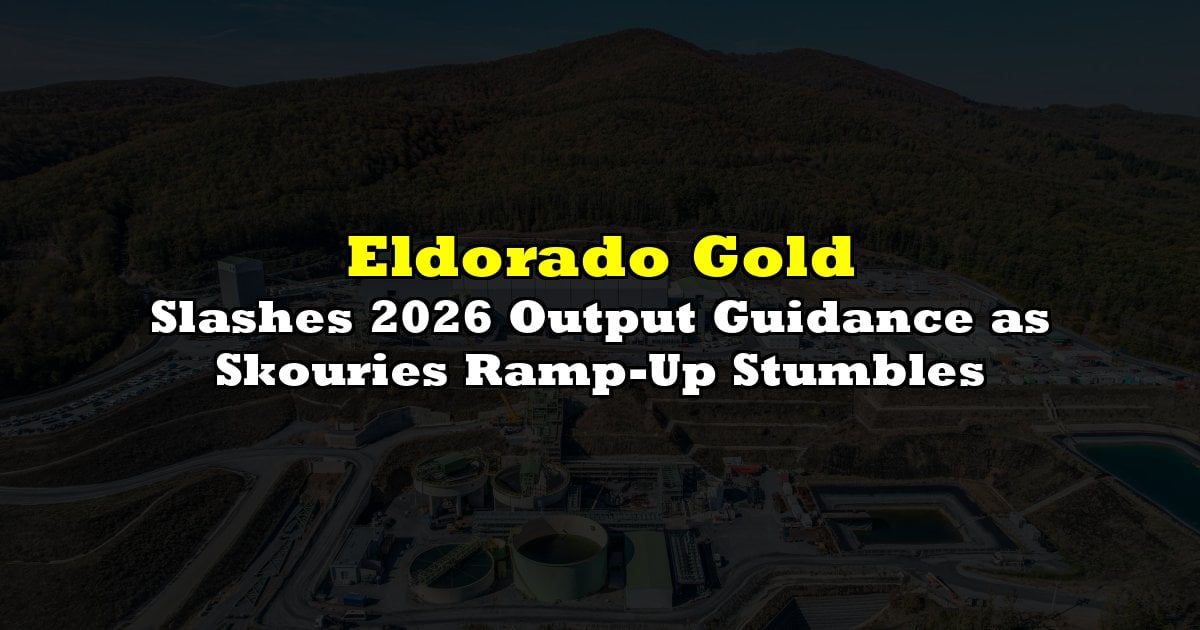

Eldorado Gold (TSX: ELD) cut its 2026 gold production outlook by close to a fifth alongside its third quarter results, as a slower than expected start at its Skouries copper-gold mine in Greece and weaker output at two existing operations overshadowed a modest lift in revenue.
Revenue for the three months ended September 30 came in at US$511.9 million, up from US$487.5 million in the second quarter on higher sales volumes. Net earnings fell to US$118.0 million, or US$0.45 per share, from US$172.8 million, or US$0.69 per share, although the prior quarter included a US$47.4 million deferred tax gain tied to a change in Turkey’s corporate tax rate.
Adjusted earnings per share slipped to US$0.49 from US$0.54, while adjusted EBITDA eased to US$275.2 million from US$281.1 million.
 Sponsored · Selkirk Copper Mines
The balance sheet is still carrying the cost of two mine builds. Free cash flow was negative US$191.1 million, an improvement on the negative US$334.1 million posted in the second quarter, but cash fell to US$396.8 million from US$554.6 million and debt climbed to US$1.99 billion from US$1.75 billion.
Gold production edged up to 106,351 ounces from 104,616 ounces, with Lamaque contributing 52,748 ounces as high grade Ormaque ore continued to support output. Total cash costs dipped to US$1,415 per ounce sold, while all-in sustaining costs rose to US$2,050 per ounce from US$1,926. Against a realized gold price of US$4,326 per ounce, margins remain wide.
The full year outlook is another matter. Eldorado now expects 425,000 to 475,000 ounces of gold in 2026, down from 495,000 to 600,000 ounces, a cut of roughly 18% at the midpoint. Skouries accounts for much of the gap, with its guidance slashed to 10,000 to 35,000 ounces from 60,000 to 100,000 ounces.
The existing mines were trimmed as well, to 410,000 to 430,000 ounces from 430,000 to 490,000 ounces, reflecting lower grades and slower mining at Kisladag and the timing of the Olympias expansion. AISC guidance for those operations rose to US$1,975 to US$2,125 per ounce from US$1,670 to US$1,870.
Skouries is also costing more. Project capital is now estimated at about US$1.425 billion, up from US$1.315 billion, partly because spending previously slated for after commercial production has been pulled forward. New chief executive Christian Milau acknowledged the ramp up “has taken longer and cost more than we expected.”
Both Skouries and the recently acquired McIlvenna Bay mine are now expected to reach commercial production late in the fourth quarter, with the latter having slipped from an earlier third quarter target.
Eldorado Gold last traded at $48.24 on the TSX.