
Honey Badger Silver (TSXV: TUF) has released an updated preliminary economic assessment for its PC Silver Mine in the Northwest Territories, outlining a 22 year underground operation that would turn out significant volumes of zinc and lead alongside silver.
The study puts the project’s after-tax net present value, at a 5% discount rate, at C$1.68 billion, with an after-tax internal rate of return of 29.3% and a payback period of 3.1 years. Those figures assume silver at US$50 per ounce, zinc at US$1.50 per pound, lead at US$0.90 per pound and copper at US$5.00 per pound.
At spot prices, including silver at US$66.41 per ounce, the after-tax NPV rises to $2.56 billion and the IRR to 38.2%.
 Sponsored · Altamira Gold Corp.
The mine plan calls for about 2,400 tonnes per day of mined material. Dense media separation would upgrade that material before roughly 1,500 tonnes per day is fed to a flotation mill at head grades of 173 g/t silver, 12.8% zinc, 9.4% lead and 0.39% copper.
Average annual payable output is estimated at 2.55 million ounces of silver, 117.2 million pounds of zinc, 94.5 million pounds of lead and 1.34 million pounds of copper, or 7.9 million silver-equivalent ounces. Output is weighted toward the early years, averaging 10.7 million silver-equivalent ounces over the first 7 years.
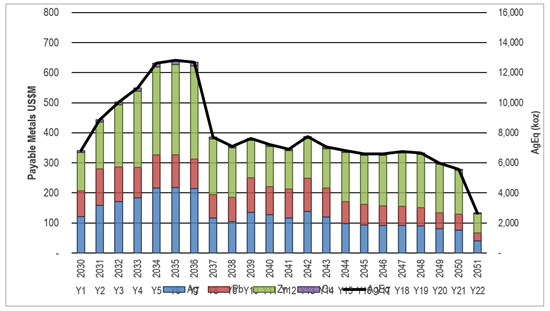
Initial capital is pegged at $667 million, including $205 million for a 170-kilometre all-season road. Sustaining capital totals C419 million over the life of the mine, while closure costs are estimated at $64 million.
By-product credits do much of the work on the cost side. All-in sustaining costs come in at negative US$22 per ounce of silver net of by-products, or US$27 per silver equivalent ounce. All-in operating costs are estimated at C$167 per tonne mined.
The site already hosts about 5 kilometres of underground workings, a historic mill and an airstrip. It is fully permitted, with impact benefit agreements in place with two First Nations. Honey Badger acquired full ownership of the asset in April.
“We view this PEA as our new starting point,” said Executive Chairman and Interim CEO Chad Williams. “The study suggests a compelling and large target production scenario, but we believe there may be an opportunity to reach that scale through a staged, and thus quicker and possibly less expensive, approach.”
The company is moving directly to a feasibility study, targeted for completion in the second quarter of 2027. That work will assess a staged start-up, capital and processing optimization, and the potential for germanium, tungsten and antimony, none of which were assigned value in the PEA.
Honey Badger Silver last traded at $0.63 on the TSX Venture.