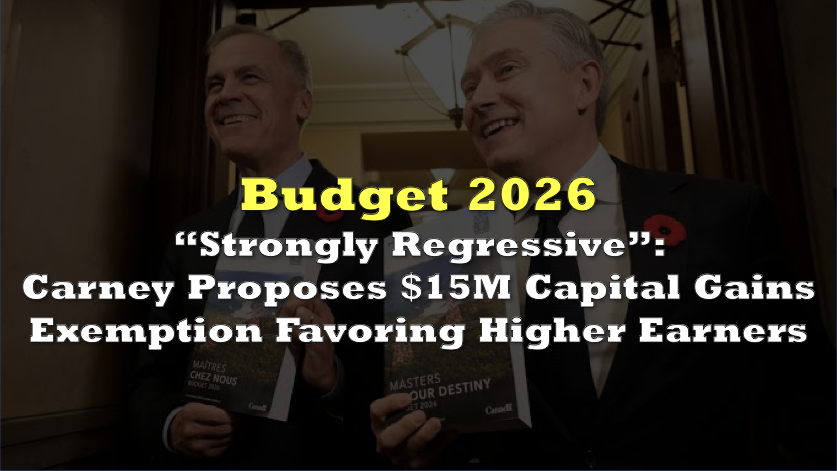

Prime Minister Mark Carney’s proposed $15 million capital-gains tax exemption is expected to benefit predominantly high-income Canadians, according to an assessment published by his own government, creating a distributional contrast within Ottawa’s plan to stimulate domestic business investment.
The federal government’s 2026 budget, tabled on Thursday introduces the Canada Growth Incentive, which would allow qualifying company founders, employees, and investors to exempt up to $15 million in capital gains from regular income taxation.
However, the budget’s accompanying Impacts Report classifies the measure as “strongly regressive,” a designation reserved for policies whose benefits are expected to accrue predominantly to higher-income individuals.
 Sponsored · Selkirk Copper Mines
According to the government’s assessment, nearly 84% of expected beneficiaries would have adjusted gross income exceeding $200,000, while more than 75% would be men.
A $565-million tax break with no overall lifetime ceiling
The exemption is projected to reduce federal revenues by $565 million through the 2030–31 fiscal year, according to the budget’s detailed tax measures.
Of that amount, $80 million is attributed to 2029–30, followed by $485 million in 2030–31. Approximately 86% of the projected five-year fiscal cost is therefore concentrated in the final year of the forecast.
The exemption would apply separately to each qualifying individual for each qualifying business, rather than imposing a single $15 million lifetime limit across all investments.
 Sponsored · Silver47 Exploration Inc.
This means an investor could potentially obtain the exemption on gains from separate qualifying businesses, provided each investment satisfies the eligibility requirements.
Ottawa has indicated that additional safeguards will prevent taxpayers from multiplying the exemption by establishing multiple corporations carrying on the same underlying business. The detailed anti-avoidance rules have not yet been released.
The incentive would generally apply to newly issued shares acquired for cash or in exchange for employment services. Eligible individuals must be at least 18 when acquiring the shares and Canadian residents during the year they claim the exemption.
Qualifying corporations must initially be Canadian-controlled private corporations with combined carrying values of assets, including those of related corporations, not exceeding $100 million when the shares are issued.
Investors must generally retain their shares for at least 36 consecutive months before selling. Other requirements govern the company’s Canadian operations and the proportion of assets used in eligible business activities.
The program also excludes several industries, including mining, agriculture, forestry, utilities, real estate, financial services, hospitality, and entertainment.
25-percentage-point increase in after-tax proceeds
The government is presenting the exemption as a way to improve Canada’s competitiveness in attracting entrepreneurs and investment capital.
In an illustration involving an Ontario founder realizing a $15 million capital gain, the budget estimates that after-tax proceeds would rise from 70.7% of the gain under existing rules to 96.0% with the proposed incentive, an improvement of 25.3 percentage points, equivalent to approximately $3.8 million in additional after-tax proceeds on the illustrated gain.
The calculation incorporates the potential impact of the Alternative Minimum Tax, which would continue to apply to qualifying gains under separate rules.
The proposed exemption would be available for qualifying shares issued from November 5, 2026, through the end of 2036, extending beyond the government’s current five-year fiscal projections.
The broader Canada Growth Incentive also includes changes allowing investors to defer capital-gains taxes when reinvesting proceeds into eligible small businesses.
Together, the exemption and rollover provisions are projected to provide $715 million in tax relief, comprising $565 million for the exemption and $150 million for the rollover changes.
The Department of Finance expects the measures to support investment, employment, and economic output. Its tax annex does not provide a separate numerical estimate of the employment or GDP increase attributable to the capital-gains exemption.
For now, the government’s own assessment establishes the anticipated distribution of the direct tax benefit, but not the eventual economic return from the foregone revenue.
Implementation will depend on the passage of the proposed tax measures and the publication of additional eligibility and anti-avoidance rules. With a minimum three-year holding period for qualifying shares, the first potential dispositions under the new exemption would generally occur in late 2029, leaving its actual investment effects and eventual fiscal cost to be assessed in subsequent years.