
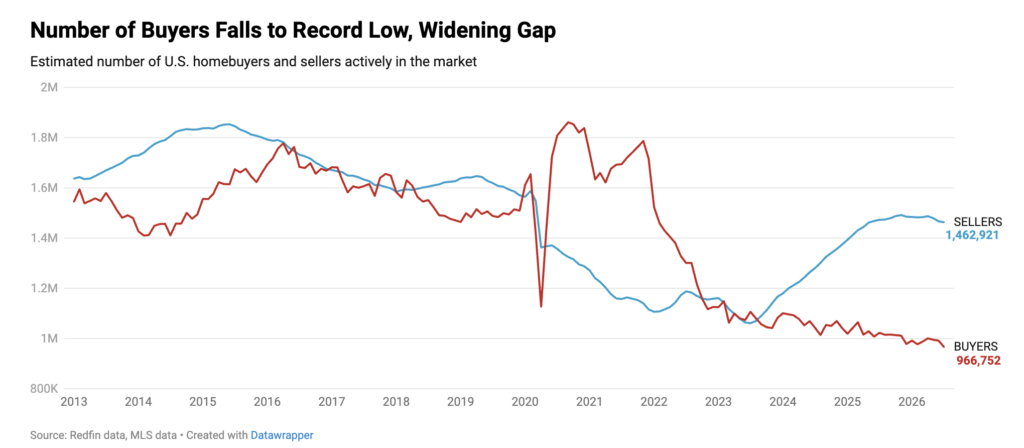
The number of active US homebuyers fell to 966,752 in July, the lowest level on record, according to Redfin. Sellers outnumbered buyers by 51.3%, just short of December’s record gap, even though the seller pool shrank too, to 1,462,921, the fewest in a year.
The gap widened for a simple reason. Buyers dropped out of the market far faster than sellers did, meaning the imbalance reflects collapsing demand rather than a flood of new listings.
The average 30-year fixed rate climbed to its highest level in a year, peaking at 6.69% in late July and early August before easing slightly to 6.67% by mid-August. The increase tracked the renewed US-Iran conflict, which pushed oil prices higher and revived inflation fears. The Federal Reserve’s move to hold rates steady at its July meeting, its third pause in a row after a run of cuts, added further pressure.
 Sponsored · Selkirk Copper Mines
Rates had been on a downward path into early 2026, briefly slipping under 6%, before reversing this summer, a fresh shock for buyers already squeezed by years of rising home values.
“Buyers are dropping out faster than sellers,” said Asad Khan, a senior economist at Redfin, noting that the buyers who stick around end up with the upper hand in negotiations. He also cited unresolved questions about the Fed’s next move and this summer’s higher borrowing costs as what’s sidelining prospective buyers.
Buyer’s-market conditions now prevail in 39 of the 49 major US metros Redfin tracked, nearly 80% of the total. Miami leads with 154% more sellers than buyers, followed by Nashville, Houston, San Antonio, and Austin.
Related: Why Are 1 in 7 Homes for Sale Nationwide in Florida?
Just six metros remain seller’s markets, led by Nassau County, New York, in areas where builders have kept new supply tight for years, and prices there are rising nearly twice as fast as in buyer’s markets.