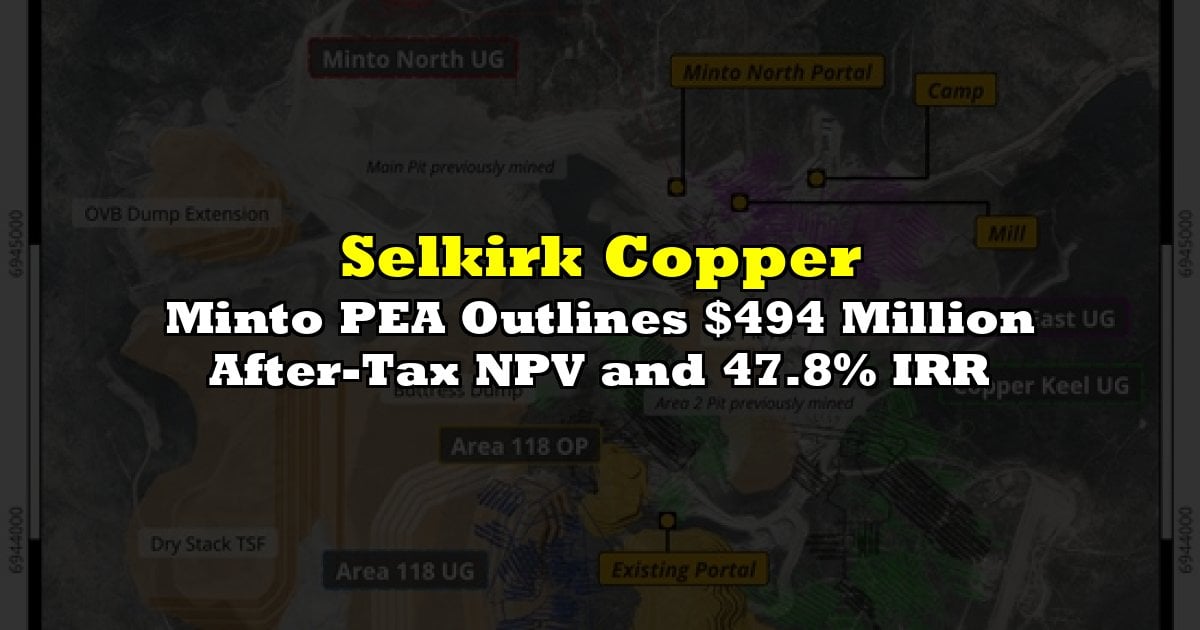

Selkirk Copper Mines (TSXV: SCMI) has released a preliminary economic assessment for the restart of its past-producing Minto copper-gold-silver mine in the Yukon. The study outlines an after-tax net present value of C$494 million and an internal rate of return of 47.8%.
Those economics use a 7% discount rate and planning prices of US$5.00 per pound copper, US$3,600 per ounce gold and US$50 per ounce silver. Payback from first production is estimated at 1.9 years.
At spot prices of US$6.50 copper, US$4,300 gold and US$65 silver, the after-tax NPV rises to C$1.02 billion. The IRR meanwhile climbs to 78.2%, and payback shortens to 1.3 years.
The study outlines a 13 year operation running at 4,100 tonnes per day through the existing mill. Feed would come from underground and open pit sources, with underground supplying all mill feed in the early years before the Ridgetop and Area 118 pits are blended in.
About 18.4 million tonnes grading 1.07% copper, 0.46 g/t gold and 4.00 g/t silver would be processed over the mine life. Peak output is expected to reach 27,200 tonnes of copper equivalent, or roughly 48,700 tonnes of concentrate grading 38% copper. Life of mine payable production totals 377 million pounds copper, 225,000 ounces gold and 1.39 million ounces silver.
Initial capital is pegged at C$186 million. That figure is kept low by what is already on site. Minto produced concentrate as recently as May 2023, and its mill, camp, power line, water treatment plant and underground development are largely in working order. Sustaining capital, including closure costs, is estimated at C$409 million.
On-site operating costs average C$95.77 per tonne milled. Copper C1 cash costs net of by-product credits come in at US$1.53 per pound, with cash operating costs of US$2.63 per pound on a copper equivalent basis, well below both the planning and spot copper prices used in the study.
President and CEO M. Colin Joudrie said the level of detail in the assessment, from integrated mine plans to cost estimates, “has increased our confidence in our ability to deliver on our focused restart timeline.”
Selkirk plans to submit amended permit applications and begin a feasibility study in the fourth quarter of 2026. An updated resource estimate is expected in the first quarter of 2027, incorporating a 50,000 metre Phase 2 drill program that is now 98% complete and was not included in the PEA mine plan.
The company is targeting a restart decision in the second half of 2027, with first concentrate in the second half of 2028 and full ramp-up by the first half of 2029.
Selkirk Copper Mines last traded at $1.72 on the TSX Venture.